Salary Partner
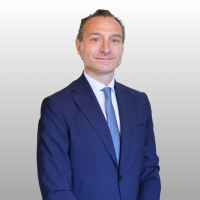
Raffaele joined LDP in 2015, after having worked with another leading Italian Tax Firm and the Italian Tax Authority. He matured a significance experience in corporate and commercial law, M&A, tax assessment and disputes, D. Lgsl. 231/2001. He is statutory auditor and member of the supervisory board of some Italian and multinational companies.

Our Team of Professionals provides timely and tailored support to companies handling cross-border contracts, tax disputes, M&A, corporate finance and GDPR compliance. As a Multidisciplinary Firm, we integrate expertise from other LDP departments, combining modern AI technologies with traditional and rigorous procedures in the legal and labour fields. This unique advantage enables us to consider all contractual tax implications during drafting and negotiation phases, delivering comprehensive and innovative legal solutions that align with your company’s needs.
Thanks to the quality of our services and the expertise of our professionals, we have earned a place on Italy’s ‘Law Firms of the Year’ list for four consecutive years, as analysed by Statista and the country’s leading business newspaper, Sole24Ore.
Yes. According to Article 2479-bis of the Italian Civil Code, a shareholders’ meeting is validly constituted even without a formal call, provided that the entire share capital participates, all directors and statutory auditors are present or informed, and no one objects to discussing the matters at hand.
Once the notice of assessment has been served, the taxpayer has 60 days to challenge it. Additionally, the taxpayer has the option to seek conciliation with the tax authorities through the Assessment with Acceptance procedure. In this case, the deadline for challenging the assessment notice is suspended for 90 days.
Yes. According to Article 2479-bis of the Italian Civil Code, a shareholders' meeting is validly constituted even without a formal call, provided that the entire share capital participates, all directors and statutory auditors are present or informed, and no one objects to discussing the matters at hand.
Once the notice of assessment has been served, the taxpayer has 60 days to challenge it. Additionally, the taxpayer has the option to seek conciliation with the tax authorities through the Assessment with Acceptance procedure. In this case, the deadline for challenging the assessment notice is suspended for 90 days.
Yes, but only in cases of serious justification. According to Article 27 of Law No. 392/1978, regardless of contractual provisions, the tenant may withdraw from the contract at any time for serious reasons, provided that a minimum of six months’ notice is given via registered letter.
It is advisable to negotiate and sign a letter of intent, summarising the general terms of the transaction, and initiate a due diligence process on the company whose shares you intend to purchase to identify any critical issues and risks, as well as any Cost Contribution Arrangements (CCAs) the enterprise is part of.
Yes, but only in cases of serious justification. According to Article 27 of Law No. 392/1978, regardless of contractual provisions, the tenant may withdraw from the contract at any time for serious reasons, provided that a minimum of six months' notice is given via registered letter.
It is advisable to negotiate and sign a letter of intent, summarising the general terms of the transaction, and initiate a due diligence process on the company whose shares you intend to purchase to identify any critical issues and risks, as well as any Cost Contribution Arrangements (CCAs) the enterprise is part of.
LDP provides Tax, Law and payroll scalable and customised services and solutions. LDP Professional have also matured a significant expertise in M&A, Corporate Finance, Transfer Price, Global Mobility Consultancy and Process Automation.
Sign up to our newsletter